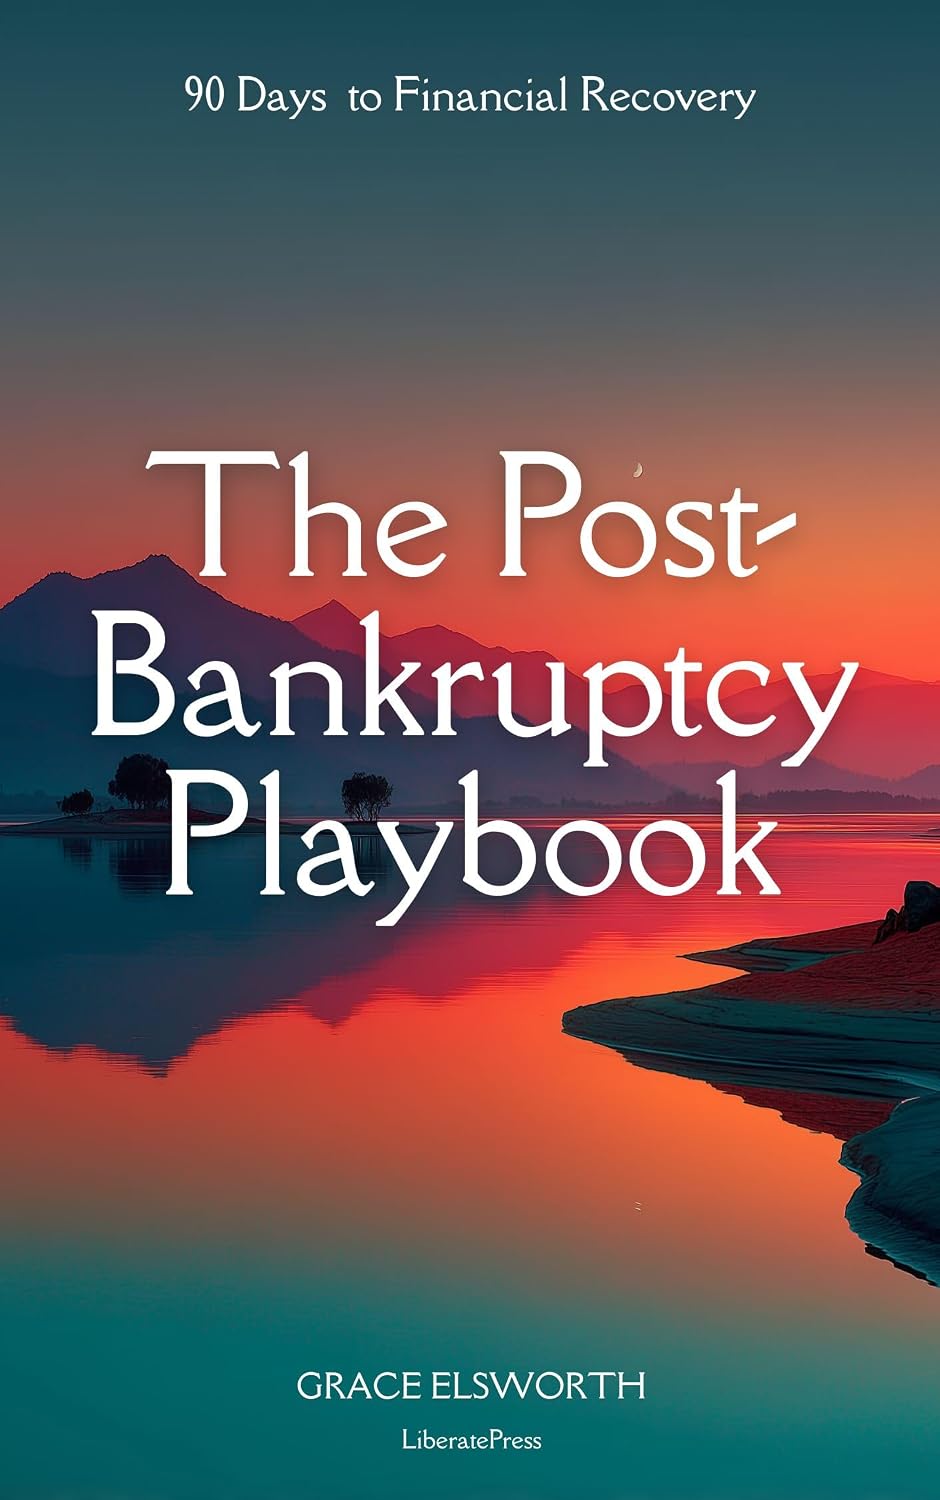
The Post-Bankruptcy Playbook may suit readers who want a structured recovery plan, but the available evidence doesn’t establish its legal completeness or results. It advertises a week-by-week 90-day action plan and a Fresh Start Budget, while its listed print length is pages Amazon.com: The Post-Bankruptcy Playbook: 90… The Post-Bankruptcy Playbook: Days to…. Treat it as general planning information, not a substitute for case-specific legal guidance.
- The book advertises a structured, week-by-week 90-day recovery plan Amazon.com: The Post-Bankruptcy Playbook: 90….
- Its Fresh Start Budget uses a 50-20-20-10 allocation Amazon.com: The Post-Bankruptcy Playbook: 90….
- The English publication is listed as pages and names LiberatePress as publisher The Post-Bankruptcy Playbook: Days to….
- The listing gives a publication date of February 17, The Post-Bankruptcy Playbook: Days to….
- The listing says screen-reader support, enhanced typesetting, Word Wise, and Page Flip are enabled The Post-Bankruptcy Playbook: Days to….
What does The Post-Bankruptcy Playbook cover during the first days?
The Post-Bankruptcy Playbook advertises a structured, week-by-week action plan for recovery over days Amazon.com: The Post-Bankruptcy Playbook: 90…. The listing describes an English publication from LiberatePress, dated February 17, 2026, with a print length of pages The Post-Bankruptcy Playbook: Days to…. The Post-Bankruptcy Playbook focuses on post-discharge habit-building and checking that bankruptcy is properly reported, rather than establishing that it covers every filing-stage procedure Life After Discharge: A Practical 12-Month….
That distinction matters because bankruptcy includes trustee review of the petition and supporting documents, a required debtor-education course, and a meeting that usually isn’t a trial The First Days Explained. In many Chapter cases, discharge occurs within about to days, while Chapter involves a repayment plan and continuing protection while payments are made The First Days Explained. The Post-Bankruptcy Playbook’s listing doesn’t provide enough evidence to verify its legal completeness, practical examples, or reader results. Its 90-day framing is clear; how thoroughly the book handles individual circumstances isn’t.
Which immediate steps should someone take after bankruptcy to protect income and meet requirements?
The Post-Bankruptcy Playbook’s general recovery framework shouldn’t displace the instructions and deadlines in your own case. Most cases include a meeting, where the filer answers basic questions under oath while the trustee confirms filing information The First Days Explained. Follow your attorney’s instructions, read court mail, and provide requested documents promptly The First Days Explained. A trustee may ask for more information about income, expenses, or property during the case The First Days Explained.
Required financial-management or debtor-education courses also matter; the cited sources describe course completion as a post-filing requirement The First Days Explained Bankruptcy discharge, how does it work?. Chapter requires particular attention to cash flow: payments begin the month after filing, even before a hearing or plan confirmation, and missed payments can lead to dismissal Chapter Bankruptcy Trustee What Can You Not Do After Filing Bankruptcies?. The trustee reviews financial information such as tax returns, pay stubs, and bank statements Chapter Bankruptcy Trustee. The Post-Bankruptcy Playbook advertises a broad recovery plan, but its listing doesn’t establish how deeply it treats Chapter procedures or Chapter obligations. Use it as supplementary structure, not as proof that a task or payment can wait.
For the Post-Bankruptcy Playbook, the evidence supports a general framework, not confirmation that it meets every court or trustee requirement Amazon.com: The Post-Bankruptcy Playbook: 90….
How can someone create a realistic 90-day budget after bankruptcy?
The Post-Bankruptcy Playbook names its budgeting approach the Fresh Start Budget and describes a 50-20-20-10 allocation Amazon.com: The Post-Bankruptcy Playbook: 90…. The available evidence doesn’t explain how those percentages are assigned or whether the method can flex for variable income, Chapter payments, or unusually high essential costs. Treat the allocation as a proposed framework, not a demonstrated fit for every household.
A workable budget should account for income, recurring bills, everyday spending, savings targets, and irregular expenses Practical Steps to Rebuild After Bankruptcy. Prioritize understanding what actually comes in and what must go out before committing to a fixed split. Tracking expenses for one or two months can reveal spending patterns and possible adjustments Practical Steps to Rebuild After Bankruptcy. A spreadsheet or budgeting app offers another route: track income and expenses, then plan to live within your means Life After Discharge: A Practical 12-Month….
The Post-Bankruptcy Playbook may give you a starting structure, while observed spending helps test whether that structure is realistic. The Post-Bankruptcy Playbook listing doesn’t show how its allocation handles unusual bills or fluctuating pay. Compare the suggested split with your recorded expenses before relying on it.
How should someone check and correct credit reports after bankruptcy?
The Post-Bankruptcy Playbook says it includes guidance for handling collector calls about discharged debts and describes collecting those debts as illegal Amazon.com: The Post-Bankruptcy Playbook: 90…. The available evidence doesn’t provide enough detail to assess the scope or qualifications of that guidance, so don’t treat a brief listing claim as a case-specific legal answer.
After discharge, check reports from Equifax, Experian, and TransUnion Life After Discharge: A Practical 12-Month…. Accounts addressed through bankruptcy should generally show a zero balance and a notation such as “Discharged in Bankruptcy” Life After Discharge: A Practical 12-Month… Practical Steps to Rebuild After Bankruptcy. If a discharged account shows an inaccurate balance or late payment, dispute the error Life After Discharge: A Practical 12-Month… Practical Steps to Rebuild After Bankruptcy.
The Post-Bankruptcy Playbook’s collector-call topic is relevant, but a debt’s continued appearance as an account with a bankruptcy notation isn’t the same as inaccurate collectible-balance reporting. The sources here don’t establish a universal date by which every discharged debt must stop appearing on a credit report. The Post-Bankruptcy Playbook should therefore be read alongside careful report review: check what the account says, identify the specific inaccuracy, and dispute that information where appropriate.
When should someone consider a secured credit card or other new credit?
The Post-Bankruptcy Playbook’s cited guidance recommends opening a secured credit card in month three, using it for a small recurring purchase, and paying the balance in full each month Life After Discharge: A Practical 12-Month…. That timing is a recommendation, not a rule that every reader should follow. If your budget can’t support full monthly repayment, taking on a new account may not fit your circumstances.
The book says its strategies—including secured cards, credit-builder loans, and authorized-user strategies—aim to rebuild a credit score by to points Amazon.com: The Post-Bankruptcy Playbook: 90…. That is an advertised aim, not a result verified by the available evidence. A secured card or credit-builder loan may help some people establish a positive payment record when managed responsibly Practical Steps to Rebuild After Bankruptcy.
Before choosing a product, compare fees, interest rates, payment expectations, and budget fit, and verify that the lender reports payment activity to the major credit bureaus Practical Steps to Rebuild After Bankruptcy. The Post-Bankruptcy Playbook’s month-three suggestion doesn’t make every offer suitable. Avoid relying on a rebuilding strategy if the lender doesn’t report activity or your budget can’t cover the balance in full. The Post-Bankruptcy Playbook doesn’t provide verified score outcomes.
Which financial actions could jeopardize a bankruptcy case or create new debt problems?
The Post-Bankruptcy Playbook’s recovery theme shouldn’t be read as permission to make financial moves without checking their effect on an active case. Debts incurred after filing aren’t included in the discharge or repayment plan What Can You Not Do After Filing Bankruptcies?. The cited guidance warns against new debt that can’t realistically be repaid, cash advances, and transfers to family or friends before filing 90-Day “Do Not” Checklist Before Filing…. After filing, avoid new debt, don’t ignore trustee requests, and complete required courses The First Days Explained.
The 90-day preference period concerns certain payments or transfers to creditors before filing; it doesn’t mean ordinary living expenses or immediate exchanges for goods and services are automatically preferences Bankruptcy Day Rule Only A Worry For…. The review period can extend to one year for insiders such as family members, business partners, or close friends Bankruptcy Day Rule Only A Worry For… What is the 90-day rule for Chapter 7…. Preference disputes can add months and increase legal costs What is the 90-day rule for Chapter 7….
The Post-Bankruptcy Playbook can’t establish whether a particular transaction is safe. In Chapter 13, opening new debt requires a motion and court approval, and refinancing property during an active Chapter or Chapter case requires court approval What Can You Not Do After Filing Bankruptcies?. Seek case-specific direction before acting.
What credit-building and savings milestones should follow the first days?
The Post-Bankruptcy Playbook says its strategies aim for a 50-to-80-point credit-score increase, but the available evidence doesn’t verify that outcome for readers Amazon.com: The Post-Bankruptcy Playbook: 90…. After the first days, focus on habits you can observe: make on-time payments for several months, check your budget regularly, keep balances low, or work toward a savings target Practical Steps to Rebuild After Bankruptcy. Those milestones are more actionable than relying on a promised score change.
Small automatic transfers into savings can build reserves over time and may reduce the need to use credit during an emergency Practical Steps to Rebuild After Bankruptcy. The listing’s title also promises to help rebuild confidence, but it provides no verified reader outcomes or savings amounts The Post-Bankruptcy Playbook: Days to…. There’s no evidence here of a guaranteed score increase, fixed savings result, or individualized legal advice.
The Post-Bankruptcy Playbook may offer structure, but treat its score target as an advertised aim rather than a forecast. The Post-Bankruptcy Playbook’s value for you depends on whether its suggested actions fit your budget and case requirements. Track habits and progress instead of assuming a specific credit result will follow.
Who is The Post-Bankruptcy Playbook best suited to, and where does it fall short?
The Post-Bankruptcy Playbook looks best suited to readers who want a week-by-week recovery framework, a named budget system, credit-report checks, and staged guidance on credit-building Amazon.com: The Post-Bankruptcy Playbook: 90… Life After Discharge: A Practical 12-Month…. Its listing doesn’t establish legal completeness or individualized advice, and the available evidence contains no product price, Amazon rating, verified buyer-review pattern, or guaranteed credit result.
You can compare its approach with a spreadsheet or budgeting app for tracking expenses, a secured card or credit-builder loan for establishing payment history, and authorized-user strategies named among the book’s options Life After Discharge: A Practical 12-Month… Practical Steps to Rebuild After Bankruptcy Amazon.com: The Post-Bankruptcy Playbook: 90…. These alternatives aren’t shown to work equally well for everyone. The listing’s accessibility details—screen-reader support, enhanced typesetting, Word Wise, and Page Flip—describe product features, not evidence of content quality The Post-Bankruptcy Playbook: Days to….
The Post-Bankruptcy Playbook is not enough on its own for an active Chapter case, disputed transfers, complex trustee issues, or questions about new debt. Follow attorney instructions and court requirements in those situations The First Days Explained What Can You Not Do After Filing Bankruptcies?.
Pros and Cons
Pros
- Advertises a structured, week-by-week 90-day recovery plan Amazon.com: The Post-Bankruptcy Playbook: 90….
- Provides a named budgeting framework, the Fresh Start Budget Amazon.com: The Post-Bankruptcy Playbook: 90….
- The listing reports screen-reader support, enhanced typesetting, Word Wise, and Page Flip The Post-Bankruptcy Playbook: Days to….
Cons
- The available evidence doesn’t verify legal completeness, practical examples, or reader results Amazon.com: The Post-Bankruptcy Playbook: 90….
- The 50-to-80-point score increase is an advertised aim, not a verified outcome Amazon.com: The Post-Bankruptcy Playbook: 90….
- The evidence doesn’t establish a product price, Amazon rating, or verified buyer-review pattern.
Final Verdict
Key Takeaways
- Use the advertised 90-day plan as a framework, not as a substitute for case-specific requirements Amazon.com: The Post-Bankruptcy Playbook: 90… The First Days Explained.
- Compare the 50-20-20-10 budget with recorded income, bills, everyday spending, savings, and irregular expenses Amazon.com: The Post-Bankruptcy Playbook: 90… Practical Steps to Rebuild After Bankruptcy.
- Review credit reports after discharge and dispute inaccurate discharged-account information Life After Discharge: A Practical 12-Month….
- Consider new credit only if the payments fit your budget and the lender reports activity to major credit bureaus Practical Steps to Rebuild After Bankruptcy.
Frequently Asked Questions
Does The Post-Bankruptcy Playbook guarantee a credit-score increase?
No verified result or guarantee is established; the book says its strategies aim to rebuild a score by to points Amazon.com: The Post-Bankruptcy Playbook: 90….
What budget method does the book describe?
It describes a Fresh Start Budget using a 50-20-20-10 allocation Amazon.com: The Post-Bankruptcy Playbook: 90….
When does the cited guidance suggest opening a secured card?
It recommends month three, with a small recurring purchase and full monthly repayment Life After Discharge: A Practical 12-Month….
What should a discharged account show on a credit report?
It should generally show a zero balance and a notation such as “Discharged in Bankruptcy”; dispute inaccurate balances or late payments Life After Discharge: A Practical 12-Month….
Is the book a substitute for attorney or court instructions?
No. The available evidence describes a general recovery plan; readers should follow attorney instructions, court mail, and trustee requests Amazon.com: The Post-Bankruptcy Playbook: 90… The First Days Explained.
Sources
- Amazon.com: The Post-Bankruptcy Playbook: Days to Financial Recovery: Rebuild Your Credit, Budget, and Confidence After Bankruptcy eBook : Elsworth, Grace: Kindle Store
- The Post-Bankruptcy Playbook: Days to Financial Recovery: Rebuild Your Credit, Budget, and Confidence After Bankruptcy (2026-10-29)
- Life After Discharge: A Practical 12-Month Roadmap to Rebuilding Your Financial Future – Brent W Davis (2025-10-18)
- The First Days Explained (2024-10-15)
- Bankruptcy discharge, how does it work? (2017-03-29)
- Chapter Bankruptcy Trustee (2025-10-28)
- What Can You Not Do After Filing Bankruptcies? (2026-07-10)
- Practical Steps to Rebuild After Bankruptcy
- 90-Day “Do Not” Checklist Before Filing Bankruptcy (2026-02-23)
- Bankruptcy Day Rule Only A Worry For Creditors (2018-01-12)
- What is the 90-day rule for Chapter bankruptcy? (2026-01-20)
Disclosure: As an Amazon Associate, I earn from qualifying purchases.