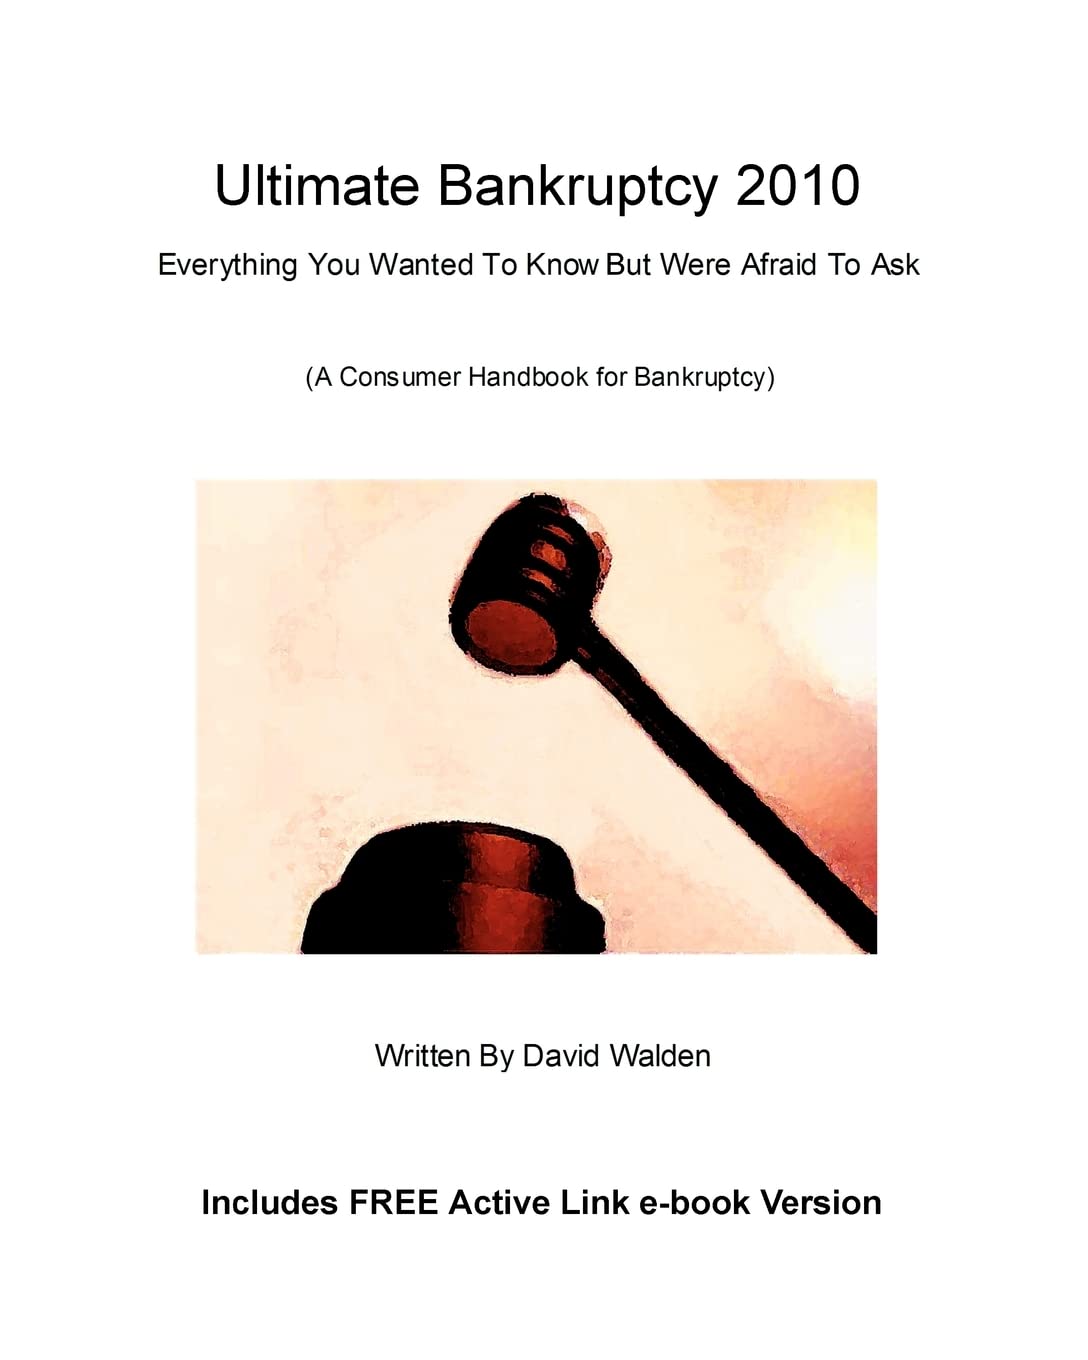
Ultimate Bankruptcy 2010: Everything You Wanted to Know About Bankruptcy But Were Afraid to Ask is worth considering for readers seeking a compact, 118-page overview of bankruptcy concepts and filing steps, especially at the listed $10.95 price Ultimate Bankruptcy 2010: Everything You Wanted…. It is not a substitute for current legal advice: the listing frames its guidance around filing in 2010, and no verified evidence of legal accuracy or buyer rating is supplied.
- The listed price is $10.95, and the book is in stock Ultimate Bankruptcy 2010: Everything You Wanted….
- The paperback has pages and is written in English Ultimate Bankruptcy 2010: Everything You Wanted….
- The publisher is CreateSpace Independent Publishing Platform Ultimate Bankruptcy 2010: Everything You Wanted….
- The listed publication date is November 12, Ultimate Bankruptcy 2010: Everything You Wanted….
- The listed dimensions are x 0.27 x inches, and the item weight is ounces Ultimate Bankruptcy 2010: Everything You Wanted….
What does Ultimate Bankruptcy cover?
Ultimate Bankruptcy 2010: Everything You Wanted to Know About Bankruptcy But Were Afraid to Ask is listed at $10.95 and shown as in stock. Ultimate Bankruptcy 2010: Everything You Wanted… The English paperback has pages, was published by CreateSpace Independent Publishing Platform, and carries a publication date of November 12, 2009. Ultimate Bankruptcy 2010: Everything You Wanted…
The listing gives the book dimensions as x 0.27 x inches and the item weight as ounces. Ultimate Bankruptcy 2010: Everything You Wanted… Ultimate Bankruptcy 2010 is framed around the point that bankruptcy filing in differed from filing before the law changes. Ultimate Bankruptcy 2010: Everything You… That framing matters if you want current guidance rather than historical context. Ultimate Bankruptcy 2010 has no supplied buyer-rating figure, and the available listing and source material provide no verified evidence of the book’s legal accuracy. The record also does not establish whether every topic is covered completely.
What does bankruptcy mean, and what types of bankruptcy were available to individuals and businesses in 2010?
Bankruptcy is a legal process that can help people regain control of their finances, but it has serious downsides and is not suitable for everyone. Bankruptcy Basics: What It Can and Can’t Do Bankruptcy can allow individuals and businesses to eliminate or restructure debts under protection from the bankruptcy court. Dischargeable Debts in Texas Bankruptcy
Ultimate Bankruptcy 2010 presents the basic chapter distinctions in a way that helps you separate liquidation, repayment, and reorganization. Chapter is described as liquidation of non-exempt assets to pay creditors, while Chapter provides a repayment plan for people with regular income. Dischargeable Debts in Texas Bankruptcy Chapter repayment can cover all or part of a debtor’s debts over three to five years. Dischargeable Debts in Texas Bankruptcy
Ultimate Bankruptcy 2010 also relates to Chapter 11, which is frequently called reorganization bankruptcy and is typically used by businesses, including corporations, sole proprietorships, and partnerships. Chapter – Bankruptcy Basics In Chapter 11, a debtor in possession generally retains control of assets without appointment of a case trustee. Chapter – Bankruptcy Basics Ultimate Bankruptcy 2010 therefore offers a chapter-level overview, not evidence that every eligibility issue is resolved.
What debts can bankruptcy discharge, and which debts generally remain after a case is completed?
A bankruptcy discharge eliminates a debtor’s personal liability for debts that qualify for discharge. Does Discharged Debt Stay Gone Forever? Ultimate Bankruptcy 2010 is useful as a starting point for understanding that discharge does not mean every obligation disappears. Child support, recent taxes, and judgments for personal injury caused by drunk driving are identified as debts that cannot be discharged. Does Discharged Debt Stay Gone Forever?
Ultimate Bankruptcy 2010 should also be read alongside the distinction between personal liability and property rights. A discharge does not by itself remove liens attached to assets before bankruptcy. Does Discharged Debt Stay Gone Forever? A lien that impairs a claimed exemption requires the debtor to file a motion seeking avoidance. Does Discharged Debt Stay Gone Forever?
Ultimate Bankruptcy 2010 cannot be assessed as a complete debt-by-debt reference from the supplied evidence because no complete discharge chart is provided. You should therefore treat the listed examples as specific categories, not as a full inventory of debts that survive or disappear. The available claims do not establish whether the book supplies case-specific analysis for secured debts, tax issues beyond recent taxes, or other exceptions.
How can someone decide whether bankruptcy is appropriate, and what alternatives should they compare?
Ultimate Bankruptcy 2010 says its steps are intended to help readers decide which bankruptcy chapter is best for them. Ultimate Bankruptcy 2010: Everything You… That purpose is practical, but bankruptcy remains a serious decision because the available source describes it as unsuitable for everyone in some circumstances. Bankruptcy Basics: What It Can and Can’t Do
The listing says many people filing for bankruptcy were being forced into Chapter and facing a five-year plan payment. Ultimate Bankruptcy 2010: Everything You… Ultimate Bankruptcy 2010 also says it focuses on maximizing a debtor’s position when Chapter is in that debtor’s best interest. Ultimate Bankruptcy 2010: Everything You… Those claims suggest attention to chapter selection and repayment consequences, although they do not prove that the book gives individualized legal advice.
Ultimate Bankruptcy 2010 should be compared with alternatives identified in the available sources, including credit counseling and debt consolidation. Bankruptcy Basics: What It Can and Can’t Do The evidence does not establish whether the book offers a complete comparison of every alternative, so you should not assume that its coverage replaces a broader options review.
What were the eligibility requirements and filing fees for Chapter and Chapter bankruptcy in 2010?
Ultimate Bankruptcy 2010 addresses a period shaped by rules enacted in 2005. People whose current monthly income exceeded their state median had to pass the means test to file Chapter 7. The New Bankruptcy Law: Changes to Chapter 7… A separate restriction concerned a prior petition dismissed during the preceding days for specified failures, or a petition voluntarily dismissed after creditors sought relief involving liened property. Chapter – Bankruptcy Basics
Ultimate Bankruptcy 2010 can be read against the available information on Chapter fee relief. With court permission, an individual debtor could pay Chapter fees in installments, with no more than four installments and the final installment generally due within days after filing. How Chapter Works — Bankruptcy Law Basics |… A court could also waive the Chapter fee when income was below 150% of the poverty level and the debtor could not pay in installments. How Chapter Works — Bankruptcy Law Basics |…
Ultimate Bankruptcy 2010 cannot be used from this record to identify the exact Chapter or Chapter filing-fee amounts in 2010. The supplied claims also do not provide a complete Chapter eligibility test. Those missing figures and rules are important if you need filing-ready guidance.
What steps did an individual need to take to file for bankruptcy, from credit counseling through discharge?
Ultimate Bankruptcy 2010 begins with approved credit counseling completed within days before filing. Chapter – Bankruptcy Basics Before filing under Chapter or Chapter 13, the debtor had to use an agency approved by the United States Trustee’s office. The New Bankruptcy Law: Changes to Chapter 7… Individual debtors with primarily consumer debts also had to file the counseling certificate and any repayment plan developed through counseling. How Chapter Works — Bankruptcy Law Basics |…
Ultimate Bankruptcy 2010 covers the Chapter filing point: the case begins when the debtor files a petition with the bankruptcy court serving the relevant area. How Chapter Works — Bankruptcy Law Basics |… The creditors’ meeting generally occurred to days after the Chapter petition was filed, and the debtor had to attend and answer questions about financial affairs and property. How Chapter Works — Bankruptcy Law Basics |…
Ultimate Bankruptcy 2010 also points to the post-filing education requirement: proof of personal financial management counseling had to be submitted before discharge. The New Bankruptcy Law: Changes to Chapter 7… The supplied evidence does not provide a complete Chapter filing checklist, so you should not treat this summary as a full procedural checklist.
How does filing for bankruptcy affect creditors’ collection actions, foreclosure, eviction, and a debtor’s property?
Filing a bankruptcy petition starts the automatic stay, which suspends many judgments, collection activities, foreclosures, and repossessions involving debts or claims that arose before filing. Chapter – Bankruptcy Basics Ultimate Bankruptcy 2010 can therefore help you understand why filing may temporarily change creditor activity. A Chapter petition automatically stays most collection actions against the debtor or the debtor’s property. How Chapter Works — Bankruptcy Law Basics |…
During the stay, creditors generally may not initiate or continue lawsuits, wage garnishments, or payment-demand telephone calls. How Chapter Works — Bankruptcy Law Basics |… Ultimate Bankruptcy 2010 should not be read as promising an absolute shield, because exceptions listed in the Bankruptcy Code exist. Chapter – Bankruptcy Basics A secured creditor may ask the court to lift the stay to foreclose when the debtor has no equity in the property and the property is not needed for effective reorganization. Chapter – Bankruptcy Basics
Ultimate Bankruptcy 2010 also needs to be read with the property-liens rule: pre-bankruptcy liens generally remain attached after discharge unless a court order avoids the lien. Does Discharged Debt Stay Gone Forever? The available claims do not provide a complete rule for every eviction or foreclosure situation.
What are the main financial and legal risks of bankruptcy, including effects on credit reports and future borrowing?
Bankruptcy has serious downsides and is not right for everyone. Bankruptcy Basics: What It Can and Can’t Do Ultimate Bankruptcy 2010 should therefore be approached as an educational guide rather than an assurance of a favorable outcome. The reported credit-report periods are up to ten years for Chapter and seven years for Chapter 13. Dischargeable Debts in Texas Bankruptcy
Ultimate Bankruptcy 2010 also relates to a practical property risk: discharge may eliminate personal liability for qualifying debts without removing liens attached to assets before bankruptcy. Does Discharged Debt Stay Gone Forever? A lien may require a court order to be avoided. Does Discharged Debt Stay Gone Forever? The available claims do not quantify future borrowing costs, approval odds, interest rates, or the full range of legal and financial consequences.
Ultimate Bankruptcy 2010 has a further limitation for readers seeking current advice because the listing frames it around bankruptcy filing in 2010, while the product record gives a publication date of November 12, 2009. Ultimate Bankruptcy 2010: Everything You… Ultimate Bankruptcy 2010: Everything You Wanted… The supplied evidence does not verify how well its guidance reflects later rules or practice.
How long did Chapter and Chapter cases typically take, and what should a debtor do after receiving a discharge?
Ultimate Bankruptcy 2010 provides only limited timing evidence in the supplied material. A Chapter creditors’ meeting generally occurred to days after the petition was filed. How Chapter Works — Bankruptcy Law Basics |… That interval is not the same as the total case duration, and the available claims do not provide typical overall durations for either Chapter or Chapter 13.
Ultimate Bankruptcy 2010 can be placed beside the stated Chapter repayment period: people with regular income could repay all or part of their debts over three to five years. Dischargeable Debts in Texas Bankruptcy That repayment period describes the plan, not necessarily the time required for every part of a case. The evidence does not supply a comparable typical total duration for Chapter 7.
Ultimate Bankruptcy 2010 also points to a requirement before discharge: the debtor had to submit proof of completing personal financial management counseling. The New Bankruptcy Law: Changes to Chapter 7… The supplied evidence does not specify a complete after-discharge checklist, including credit-report review, lien handling, or future borrowing steps. You should treat those omissions as unknown rather than assume the book covers them fully.
Pros and Cons
Pros
- The book covers bankruptcy chapter distinctions, including Chapter liquidation, Chapter repayment, and Chapter reorganization Dischargeable Debts in Texas Bankruptcy Chapter – Bankruptcy Basics.
- The listing says its steps are intended to help readers decide which bankruptcy chapter is best for them Ultimate Bankruptcy 2010: Everything You….
- The 118-page English paperback is listed at $10.95 and in stock Ultimate Bankruptcy 2010: Everything You Wanted….
- The available material addresses filing steps, credit counseling, the creditors’ meeting, and discharge-related education Chapter – Bankruptcy Basics How Chapter Works — Bankruptcy Law Basics |… The New Bankruptcy Law: Changes to Chapter 7….
Cons
- The book is framed around bankruptcy filing in 2010, and its publication date is November 12, 2009, limiting confidence that it reflects current advice Ultimate Bankruptcy 2010: Everything You… Ultimate Bankruptcy 2010: Everything You Wanted….
- The supplied evidence does not provide a buyer-rating figure or verified evidence of the book’s legal accuracy.
- The available claims do not provide exact Chapter or Chapter filing-fee amounts How Chapter Works — Bankruptcy Law Basics |….
- The supplied evidence does not provide a complete Chapter filing checklist, a complete debt-discharge chart, or typical total case durations.
Final Verdict
Key Takeaways
- Treat the book as a compact overview of bankruptcy chapters, procedures, and risks, not as verified current legal advice.
- Check eligibility carefully: Chapter means testing, prior-petition restrictions, and fee-relief rules are not interchangeable.
- Remember that discharge addresses personal liability and does not automatically remove pre-bankruptcy liens.
- Compare bankruptcy with credit counseling and debt consolidation before filing.
- Do not assume the supplied evidence provides complete Chapter procedures, total case durations, or an after-discharge checklist.
Frequently Asked Questions
Is Ultimate Bankruptcy a current legal guide?
Ultimate Bankruptcy is framed around filing in 2010, and its listed publication date is November 12, 2009. Ultimate Bankruptcy 2010: Everything You… Ultimate Bankruptcy 2010: Everything You Wanted… The supplied evidence does not verify that its guidance reflects current law or practice.
How many pages does Ultimate Bankruptcy have?
Ultimate Bankruptcy has pages. Ultimate Bankruptcy 2010: Everything You Wanted…
What does a bankruptcy discharge remove?
A bankruptcy discharge eliminates personal liability for dischargeable debts, but liens attached to assets before bankruptcy generally remain unless a court order avoids them. Does Discharged Debt Stay Gone Forever?
How long can Chapter repayment last?
Chapter allows individuals with regular income to repay all or part of their debts over three to five years. Dischargeable Debts in Texas Bankruptcy
What is the listed price and availability?
The book is listed at $10.95 and shown as in stock. Ultimate Bankruptcy 2010: Everything You Wanted…
Sources
- Ultimate Bankruptcy 2010: Everything You Wanted to Know About Bankruptcy But Were Afraid to Ask (2026-10-20)
- Ultimate Bankruptcy : Everything You Wanted to Know About Bankruptcy but Were Afraid to Ask by Walden, David; Dicarlo, Donald: As New Soft cover (2009) (2026-10-20)
- Bankruptcy Basics: What It Can and Can’t Do
- Dischargeable Debts in Texas Bankruptcy (2024-12-04)
- Chapter – Bankruptcy Basics
- Does Discharged Debt Stay Gone Forever?
- The New Bankruptcy Law: Changes to Chapter and – Sycamore Community Schools EAP
- How Chapter Works — Bankruptcy Law Basics | Bankruptcy Law Center (2018-04-25)
Disclosure: As an Amazon Associate, I earn from qualifying purchases.